The seed round
Eight years of the unglamorous part, and the rulebook finally arrived.
Stobox has been structuring real-world assets since 2018, through the years when nobody was buying. The regulation that makes this a market landed in 2026, and the work that takes eight years to do is already done.
Why now
The market just became legal, and we are already in the room.
Three things had to be true at once. They are, and the order they happened in is the whole argument.
The rulebook landed
Tokenized securities went from a question counsel could not answer to a procedure with a filing. That is the change that turns an experiment into a market.
Institutions moved first
The largest asset managers in the world tokenized funds before the rules were settled. The demand side did not wait, which is unusual and worth noticing.
We backed the standard
Stobox is a backer of ERC-7943, the permissioned token standard the market converged on, and issues on it. Being early to a standard is only useful if you are still there when it wins.
Tokenized real-world assets on-chain
The record
Not a thesis. A live track record.
$305M+ in assets structured and supported for 100+ clients across 20+ jurisdictions since 2018, through a full lifecycle rather than to a signature. FY2024 was GAAP-profitable.
Three products, one client
The record, the raise and the token. A client who buys one usually needs the next, which is why the revenue per client compounds without new acquisition.
Never a cut of the raise
Published flat fees at every layer. We are not paid more because a client raises more, which removes the incentive that makes most of this industry untrustworthy.
Margin that scales past headcount
The specialists do the part that needs judgement. The software does the part that does not, and that part is most of it.
Where we sit
Three products, in the order the work happens.
A company that is not organized cannot raise, and a raise that is not prepared cannot be tokenized into anything a counterparty accepts. Most of this market sells the third job. We do all three, and the first is free to start.
Organize
Intelligence
One canonical, verifiable record of the company, scored across seven readiness pillars. This is the part that decides whether anything after it is worth doing.
Raise
Raisable
The record becomes a broker-acceptance-grade offering. Documents are prepared from it and finalised by specialists, and the sale runs through licensed broker-dealers.
Tokenize
Compass
The security is issued permissioned, with an asset passport, and the compliance is enforced by the token rather than by a policy written beside it.
Eight years of rooms
Being early is only useful if you are still there.
Conferences, regulators, summits and client sites since 2018. This is what the unglamorous part looks like in the years when nobody is buying.


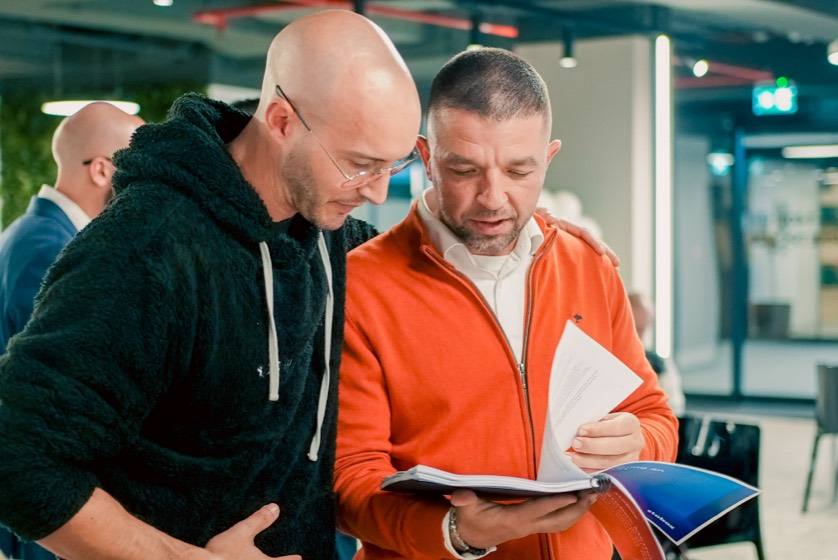
Stobox events and appearances, 2018 to 2026.
Proof, not promises
We tokenized our own equity on our own rails.
STBX runs on Stobox Compass, the same compliant stack we sell. Our cap table is on our own software, which means a defect in it is a defect in our own ownership record. The two things a reader should not have to take on trust are the valuation and the licensing, and neither is ours.
The valuation is not ours to declare
Stobox Technologies Inc. is tracked by Eqvista’s Real-Time Company Valuation, a market-based estimate applied continuously rather than once a year. It benchmarks against real funding rounds, secondary transactions and revenue multiples of comparable private companies. It is a professional estimate, not a live quote, and it is separate from the company’s 409A.
The round runs on licensed rails
The Reg D 506(c) offering is supported by Silicon Prairie, a FINRA-registered broker-dealer and SEC transfer agent. It runs accreditation checks, KYC and AML, escrow and subscription documents end to end, and maintains the official share register. Stobox does none of that itself, because Stobox is not licensed to.
The round
One million, at seventeen and a half pre-money.
The first tranche is $1,000,000. The pre-money valuation is $17.5M, set by the company and anchored to actual FY2025 revenue, which is a different number from the continuously updated Eqvista estimate above and should not be confused with it. Price per share, share class and minimums are in the offering documents, not on this page. Which rail applies to you is decided by where you are and how you are verified.
Path 01 · Traditional securities
Reg D 506(c)
Verified US accredited investors
- A FINRA-registered broker-dealer and an SEC transfer agent are the licensed rails of record for the offering.
- Accreditation checks, KYC and AML, escrow and subscription documents run end to end through them, not through us.
- The official share register and cap table are maintained by the transfer agent, audit-ready.
- General solicitation is permitted under the exemption, which is why you can read this page at all.
- Not open yet. The subscription portal is being finalised. Nothing can be subscribed for on this rail today.
Reg D 506(c) · verified accredited investors
The subscription portal is being finalised with Silicon Prairie. Write and we
email you the day it opens.
Path 02 · On-chain
STBX, tokenized Class-C shares
Qualified non-US investors, where permitted
- Equity issued and held on-chain, with the compliance encoded into the asset rather than written beside it.
- A private placement of our own equity, offered directly by its issuer, Stobox Tokenized Equities Ltd.
- US$2.00 per token, settled on-chain, live on Arbitrum since 2025.
- Open now at stbx.stobox.io, and not available to US persons.
- Identity verified before a token can move, and transfer rules enforced by the token itself.
STBX · tokenized Class-C equity
Solely through the Offering Documents on Stobox Compass
From Gene Deyev
Why I would rather you read this twice.
The founder and chief executive, on what this is and what it is not.
We started this in 2018, when tokenizing a real asset was a thing you had to argue for in every single meeting. For most of those eight years the honest answer to why now was that it was not now yet, and we built the unglamorous parts anyway: the record, the exemptions, the transfer rules, the work in twenty jurisdictions that nobody puts on a slide.
The rules arrived in 2026 and the largest asset managers in the world moved before they were finished. That is the change. It is also the reason we will not tell you this is safe. It is a private company in a market that has just become legal, and both halves of that sentence carry risk.
What we will tell you is what we have: revenue from three products against one client, a valuation set by somebody who is not us, a cap table running on our own software, and no incentive to talk you into a bigger raise, because we have never taken a percentage of one.
Gene Deyev Founder and Chief Executive, Stobox Technologies Inc.
Read this part
What you are taking on.
Private companies fail, and most of them do. Everything on this page is a reason we think this one will not, which is not the same as evidence that it will not.
FY2024 was GAAP-profitable. We do not claim a track record of profitability, because one year is not one.
There is no promise of a market. A path to secondary trading through licensed venues exists; listing decisions rest with the venue.
This page is a description. The Reg D offering and the STBX private placement each run under their own documents, and where those differ from anything here, they govern.
The legal position
Said plainly, and in the frame rather than in small print.
If any of this is a surprise at the end of the page, the page was written badly.
Not investment advice
- Nothing on this page is investment advice, a recommendation, or an offer to sell or a solicitation of an offer to buy any security. It is a description of a company and of an offering that exists under its own documents.
- The Reg D 506(c) offering is open to verified accredited investors only. Accreditation is verified by a licensed broker-dealer, not self-certified, and general solicitation is permitted under that exemption, which is why this page may be read publicly.
- Stobox Technologies Inc. is not a broker-dealer, not an investment adviser, not a transfer agent and not a law firm. Regulated activity in the round is performed by licensed parties under their own registrations.
- Terms that bind are in the offering documents. Where anything on this page differs from them, they govern, and you should read them before you decide anything.
- Forward-looking statements on this page describe what we intend, not what will happen. Private companies fail. You may lose the entire amount you invest.
- There is no promise of a market. A path to secondary trading through licensed venues exists for the tokenized route, and listing decisions rest with the venue.
Talk to a person
Before you decide anything.
The round is open to verified accredited investors. If you want the documents, the data room, or an hour with the people who would spend the money, ask.
Ask about the round
The documents and the data room
Verified accredited investors
Or write to info@stobox.io
Read first
What the instrument actually is
The STBX term sheet, in full
And the valuation method at /valuation
Straight answers
The questions that decide it.
What am I buying?
Equity in Stobox Technologies Inc. Two routes exist and both give you the same underlying ownership: a Reg D 506(c) subscription through a FINRA-registered broker-dealer for verified US accredited investors, or tokenized Class-C shares as STBX for qualified non-US investors, offered directly by their issuer.
Is Stobox profitable?
FY2024 was GAAP-profitable. That is one audited year in a company that has been operating since 2018, and it is the honest way to say it: profitable once, not profitable throughout.
Where does the revenue come from?
Three products against one client: the record, the raise and the token. We charge published flat fees for each and never take a percentage of what a client raises, at any layer, at any point.
How is the valuation set?
Independently, not by us. The valuation page carries the method and who did it.
What happens if the market does not arrive?
You lose your money. That is the honest answer. The rulebook landing and institutions moving are reasons to believe the market is arriving, not guarantees that it will, and eight years of work does not entitle anyone to a return.
Can I sell?
Assume not. This is private equity in a private company. There is a path to secondary trading through licensed venues for the tokenized route, and the venue decides whether to list.
Two ways in
Before you look at ours, look at yours.
The same readiness score we run on every client asset, free, about eight minutes, and nobody calls you unless you ask.
Prefer email? info@stobox.io.
Or bring the asset itself – thirty minutes, and we will say if the answer is no.
Stobox Technologies Inc. These are the author’s pages, not legal, tax or investment advice, and not an offer to sell or a solicitation to buy any security. See the privacy summary.